

Vault12: Inherit Crypto Wallet
4.3

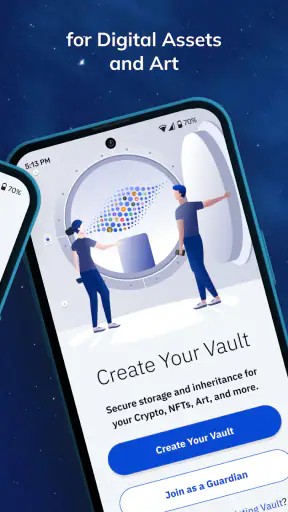
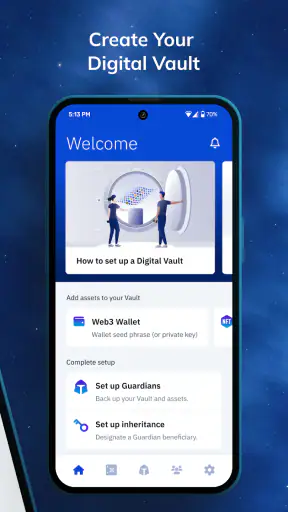
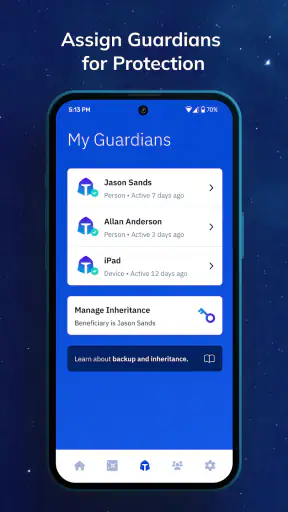
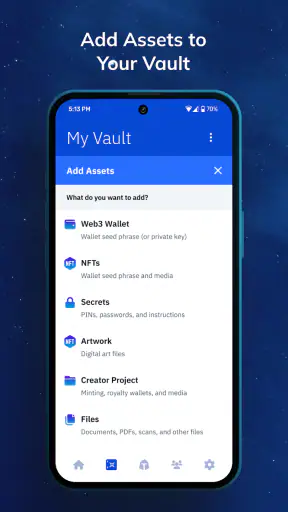
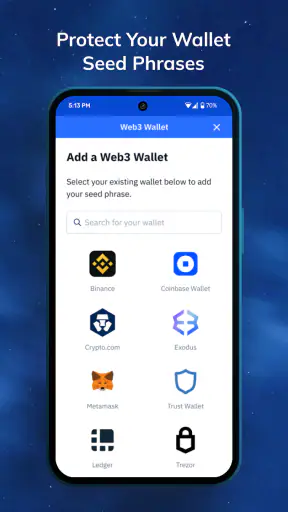
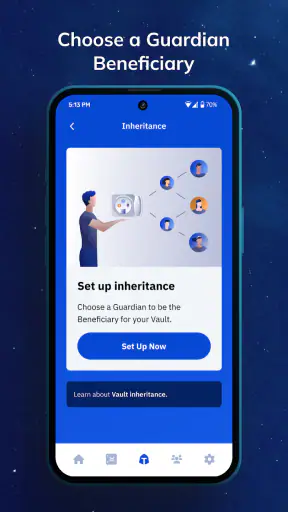
Crypto inheritance sounds like a distant concern until a household has to answer a very practical question: who can reach digital assets if the owner is unavailable? I found Vault12: Inherit Crypto Wallet most interesting in that space. It is a finance app from Vault12, Inc, built around backing up and passing on Bitcoin, Ethereum, Solana, stablecoins, and other crypto assets. That focus makes it quite different from a normal spending wallet, exchange app, or portfolio tracker.
My first impression was that this is not an app I would install simply to make everyday payments faster. Its value appears when ownership, recovery, and family coordination matter more than quick transactions. The free download makes it easy to examine, while optional purchases priced from $19.99 to $29.99 per item mean I would still read the in-app terms carefully before committing to a long-term inheritance plan.
The app is rated for Everyone, has reached over 100K installs, and holds a 4.3 average from roughly 891 ratings. Those figures suggest a real user base without making Vault12 feel like a mainstream banking replacement. It was released on August 28, 2019, and version 3.0.0 requires at least iOS or Android 12, so device compatibility is the first household check I would make.
How Vault12 fits a shared household
A realistic use case is a couple who keeps crypto in one person’s name but manages household finances together. One partner may understand seed phrases, wallet addresses, and network choices, while the other knows that the assets exist but would not know where to begin during an emergency. In that situation, a backup and inheritance-focused tool can give the conversation a clearer shape than leaving a handwritten note beside a laptop.
I would not treat a shared phone or tablet as automatically shared ownership, though. Installing the app on a family device does not by itself explain who should be able to see balances, recovery material, or inheritance arrangements. The important first step is deciding whose assets are being protected and which person is responsible for maintaining the plan. That boundary should be agreed on before anyone starts entering information.
This distinction matters because crypto is unusually unforgiving about confusion. A banking app often gives a household recognizable account names, statements, and a support route. A crypto wallet can involve several networks and different address formats, so a well-meaning relative may not know whether an asset belongs in Bitcoin, Ethereum, Solana, or a stablecoin account. I would use Vault12 as part of a written household process, not as a substitute for explaining the basics to the people who may eventually need it.
For a single owner, the shared-use scenario can be more limited but still useful. You might keep the app on your personal phone while arranging inheritance with a spouse, sibling, or trusted adviser. In that case, the app’s role is less about simultaneous access and more about making sure the recovery plan does not depend entirely on one person remembering every detail.
The strongest household benefit is coordination around access, not convenience during daily spending. That is an important expectation to set. If your main goal is buying coffee, swapping tokens, or checking a live market price, a conventional wallet or exchange will probably feel more direct. Vault12 makes more sense when you are deliberately preparing for loss, incapacity, or transfer.
Starting without blurring account boundaries
Before setup, I would make a simple inventory outside the app. Write down which assets exist, which networks they use, and who legally or practically owns them. I would also separate personal holdings from shared household money. That preparation reduces the chance of treating every token visible on one device as one undifferentiated family pool.
Another useful boundary is between the owner and the person being prepared to help. The owner should decide what can be shared, when it can be shared, and what information is necessary for recovery. Giving someone unrestricted access merely because they live in the same home is not a safe default. At the same time, hiding the existence of the plan so thoroughly that nobody knows where to look defeats the purpose of inheritance preparation.
Vault12 is best approached as a deliberate setup rather than a quick registration. I would choose a quiet moment, avoid a public or work device, and make sure the phone’s operating system meets the app’s requirement. I would also avoid creating a plan while distracted by children, guests, or a busy household routine. A mistake in a backup workflow can remain invisible until the moment it is needed.
One non-obvious trade-off is convenience versus separation. A single family tablet may make coordination easier, but it can also expose sensitive information to anyone who uses that tablet. A personal phone gives better separation, yet a recovery plan stored only there may be harder for others to locate. I would keep the app on the device controlled by the asset owner and document, separately and securely, how an authorized person should begin the recovery process.
I would also resist the temptation to add every relative as a participant before understanding the arrangement. More people can mean more communication, but it can also create uncertainty about who is expected to act. A smaller, clearly defined circle is easier to brief and less likely to produce conflicting instructions.
Coordinating crypto across different networks
The app’s coverage of Bitcoin, Ethereum, Solana, stablecoins, and other crypto is useful because households rarely hold just one kind of asset. It also creates a responsibility that a basic inheritance note might overlook: the network matters. An Ethereum token and a Solana token are not interchangeable simply because both are displayed as digital assets, and sending funds through the wrong network can create serious problems.
My practical advice is to keep a plain-language asset map alongside the app. For each holding, note the asset name, the network, and the wallet or account where it is held. Do not rely on a symbol alone. Stablecoins are a particularly good example: the same broad label can refer to assets operating on different networks, with different handling requirements. This kind of external note is not a replacement for Vault12; it is the context that helps a future user interpret the backup correctly.
Another useful workflow is a scheduled household review. I would revisit the plan whenever assets move between wallets, a new network is added, or the person responsible for the arrangement changes. A backup made at the beginning of the year can become misleading after several transfers. The app can support the inheritance structure, but it cannot make an outdated inventory accurate.
Coordination also means explaining what not to do. A relative who discovers a recovery plan may feel pressure to test it immediately. I would make clear that experimenting with a live wallet, moving a small amount “just to check,” or importing recovery details into an unrelated app can introduce unnecessary risk. The safer approach is to understand the instructions first, confirm the destination and network, and seek qualified help when the value or complexity justifies it.
This is where Vault12 compares favorably with a simple password manager entry or paper note. Those alternatives can preserve text, but they do not necessarily encourage a crypto-specific inheritance workflow. On the other hand, a paper document can be easier for a nontechnical family member to understand at a glance, and a password manager may fit better for someone who already has a carefully maintained digital estate plan. I see Vault12 as a focused layer, not a universal replacement for every record-keeping tool.
Trust, age, and the people involved
The Everyone age rating makes the app broadly approachable from a store perspective, but that should not be confused with every household member being suitable to manage crypto inheritance. Age is only one part of trust. The better questions are whether the person is dependable, can follow network-specific instructions, respects privacy, and will ask for help instead of improvising.
I would not place a child in charge of a serious household recovery plan just because they are comfortable with phones. A teenager may understand apps better than an older relative while still lacking the judgment to handle irreversible transfers. Conversely, an older family member may be highly trustworthy but need a slower explanation and a printed orientation note. The app does not remove the need to match responsibility with capability.
For couples, I would recommend discussing access while both people are calm and available. The conversation should cover where the plan is kept, who should be contacted, and how to distinguish genuine instructions from a scam. For siblings or friends, I would be even more precise about the limits of their role. Trust should be explicit, not assumed because someone is close to the owner.
Shared-device use deserves special caution. I would not leave the app open on a tablet used by guests, nor would I let a family member casually browse it without knowing what information may be visible. If several people use one device, the household needs clear personal boundaries around screen access, notifications, and stored material. Since I would not rely on a shared device as the only recovery route, I would keep the broader instructions in a separate, controlled location.
There is also an emotional side to inheritance planning. Talking about incapacity or death can make people postpone the task, and a complicated crypto vocabulary can make relatives disengage. I found the app’s narrow purpose helpful as a conversation starter, but I would introduce it with ordinary language: what exists, why access matters, and what the trusted person may need to do. That approach is more effective than presenting the app as a technical solution and expecting everyone else to learn crypto under pressure.
Where the app may not be the right fit
I would skip Vault12 if I only wanted a straightforward wallet for regular transfers. Its inheritance angle may feel like extra structure when all you need is a small spending balance. I would also hesitate if your household cannot agree on ownership or trusted contacts. No application can resolve a dispute about who should control assets, and adding more software may simply hide that unresolved problem.
It may also be a poor match for someone who prefers a fully offline process. A carefully prepared paper plan, stored securely and updated by hand, can be easier to audit for a person who does not want sensitive arrangements tied to an app workflow. The trade-off is maintenance: paper becomes stale quickly when wallets or networks change, while a digital process may be easier to revise.
Another limitation is the need to understand the paid path before building your entire estate plan around it. The app itself is free, but optional purchases range from $19.99 to $29.99 per item. I would first explore the available flow, identify which parts are included, and only then decide whether a purchase matches the household’s needs. The right question is not whether the upgrade sounds useful; it is whether it produces a plan your chosen successor can actually follow.
Device requirements can matter in a multigenerational home as well. Because version 3.0.0 requires OS 12 or later, an older phone may not be suitable for the person expected to help with recovery. I would check every relevant device before assigning responsibility. If the trusted person cannot use the app when needed, the household should prepare an alternative set of instructions rather than discovering the compatibility issue later.
Finally, I would not confuse a backup arrangement with legal estate planning. Depending on where you live, ownership, taxes, wills, and inheritance rules may require professional advice. Vault12 can be part of the operational side of passing on crypto, but it should sit alongside the legal and personal documents that establish who is entitled to receive it.
My household verdict
After looking at Vault12 through a shared-home lens, I see a focused finance app for people who want to make crypto inheritance less dependent on one person’s memory. Its support for several major asset types gives it a practical role in mixed portfolios, and its free entry point makes it reasonable to investigate before deciding whether the optional purchases are worthwhile.
I would recommend it to a crypto owner who has moved beyond casual experimentation, holds assets across more than one network, and wants a structured conversation with a spouse or trusted successor. I would pair it with an external asset inventory, clear ownership notes, and a calm explanation of what the designated person should do. That combination is much stronger than installing the app and assuming the household is protected.
I would not recommend treating it as a family wallet, a daily spending tool, or a magic answer to trust problems. Shared devices need boundaries, relatives need practical guidance, and every network-specific detail needs to be checked before funds are moved. The app’s Everyone rating makes it accessible, but responsible use still depends on maturity and judgment.
Overall, I think Vault12: Inherit Crypto Wallet earns its place when the problem is continuity: making sure a trusted person can understand and act on a crypto owner’s plan. It is less compelling when the problem is trading, payments, or simple storage. If your household is willing to define ownership, limit access sensibly, and review the arrangement after major wallet changes, this app can be a useful part of that process. If not, a simpler written plan or a different wallet may be the more honest choice.
4.3
130.00 Reviews
Pros
- Private keys are encrypted and kept under your control.
- Supports inheritance planning for digital assets.
- Designed to help trusted contacts access funds when needed.
- Adds an extra layer of protection against device loss.
- Useful for organizing long-term crypto security plans.
Cons
- Requires careful setup of recovery and inheritance contacts.
- Mistakes in wallet details may complicate asset recovery.
- Security depends partly on protecting your devices and backups.
- May feel complex for users new to cryptocurrency wallets.
- Inheritance features may require trust in the chosen contacts.


